Korea Investment Securities cut 2026-27 operating profit forecasts for SK Hynix by 9-11% The July 13 note still maintains a Buy rating with a 3.8 million KRW target, but highlights a 2Q reality check: weaker HBM sales mix, slower ASP growth, and HBM4 ramp delays. A consensus
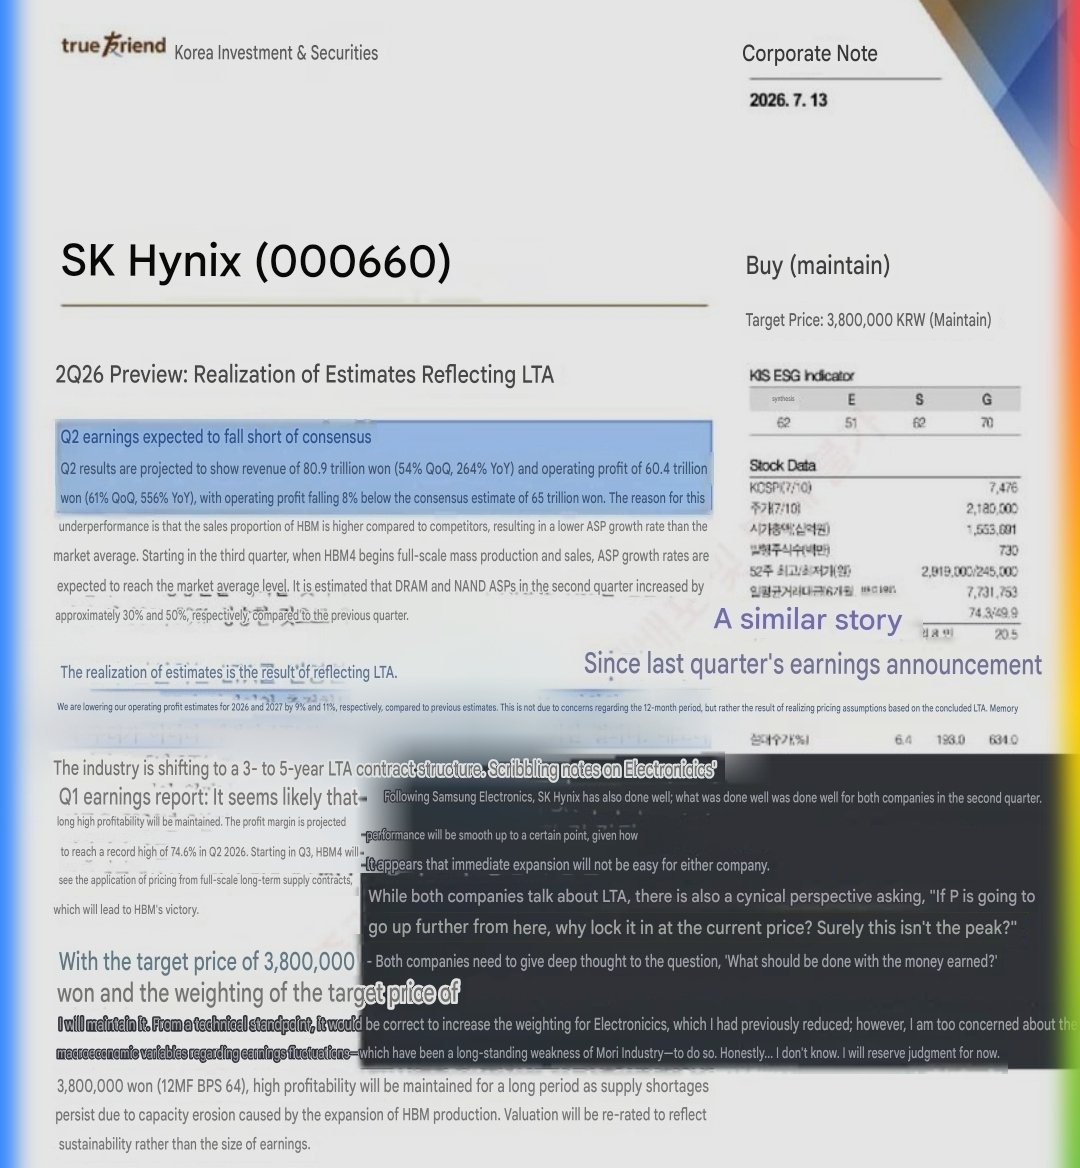
Semiconductor Insider — Korea Investment Securities cuts SK Hynix 2026-27 operating profit 9-11% on HBM4 ramp delays
The catalyst under today's memory selloff. A July 13 sell-side note cuts SK Hynix operating profit 9-11% citing weaker HBM sales mix, slower ASP growth, and HBM4 ramp delays — a 2Q reality check on the exact mechanism the memory-supercycle thesis rests on (HBM tightness cannibalizing DRAM). Buy rating maintained; this is a mix/timing cut, not a demand cut.
Why it's worth your time
The catalyst under today's memory selloff. A July 13 sell-side note cuts SK Hynix operating profit 9-11% citing weaker HBM sales mix, slower ASP growth, and HBM4 ramp delays — a 2Q reality check on the exact mechanism the memory-supercycle thesis rests on (HBM tightness cannibalizing DRAM). Buy rating maintained; this is a mix/timing cut, not a demand cut.
Related
8 eventsSource links
Tweets, videos, filings, articles, and source pages tied to this read.